
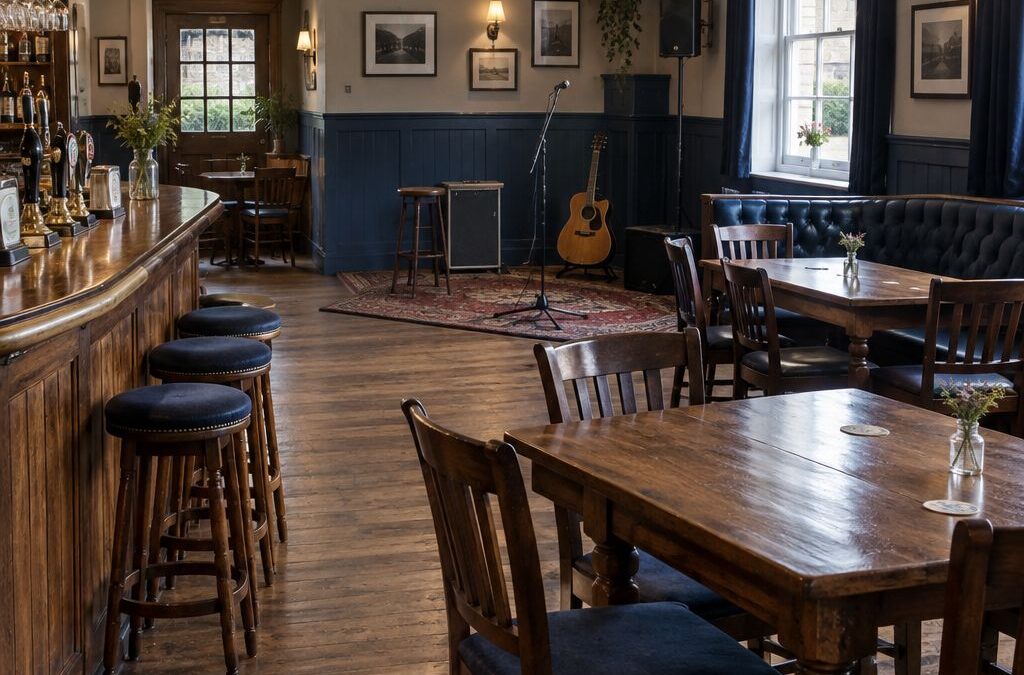
Qualifying pubs and live music venues in England receive a 15% discount on their 2026-27 business rates bills, applied by their council on top of the lower retail, hospitality and leisure (RHL) multipliers that took effect on 1 April 2026. The government values the package at £1,650 for the average pub in 2026-27, and qualifying bills are then frozen in real terms for 2027-28 and 2028-29. The catch: the council decides eligibility against fixed criteria, so a pub that thinks it qualifies but shows no discount on its bill needs to ask why.
- Qualifying pubs and live music venues in England get 15% off 2026-27 business rates.
- The 15% relief sits on top of the lower RHL multipliers that replaced the old relief scheme.
- The government values the support at £1,650 for the average pub in 2026-27.
- Councils apply the relief automatically — if it is missing, apply with your rates reference.
- A rateable value error can still be challenged even after relief is applied.
Why pub rates changed in 2026
The 2026 revaluation reset every rateable value on 1 April 2026, and the temporary retail, hospitality and leisure relief — 40% and capped at £110,000 in 2025-26 — ended on 31 March 2026. It was replaced by a permanent set of five multipliers. A pub with a rateable value below £51,000 now pays 38.2p in the pound instead of 43.2p, and one between £51,000 and £499,999 pays 43p instead of 48p. Properties at £500,000 or above pay 50.8p.
On top of that, the Treasury announced a dedicated pub and live music venue relief on 27 January 2026: a 15% reduction on eligible bills for 2026-27, with bills frozen in real terms for the following two years. Multipliers may differ in the City of London, and your council decides which properties qualify against the statutory definitions.
Pub and live music venue relief: who qualifies in 2026-27
A property must be in England and meet all of the following, as councils publish the criteria:
- Wholly or mainly used as a pub or a live music venue — food sales, music or other activities must be ancillary to the main use
- Open to the general public, allowing free entry other than when occasional entertainment is provided
- Drinking is permitted without requiring food to be consumed
- Drinks can be purchased at a bar
- A live music venue must be wholly or mainly used for live music performances to entertain an audience
Councils award the relief automatically where they believe the criteria are met, and it should appear on the 2026-27 annual bill. If no discount is showing but you believe you qualify, you can apply to your council with your business rates reference and the reasons you meet the criteria.
How the 15% relief stacks with the other 2026-27 support
| Support | What it does | Who gets it |
|---|---|---|
| RHL multipliers | Lowers the rate from 43.2p/48p to 38.2p/43p | Qualifying pubs, bars and hospitality properties below £500,000 RV |
| Pub and live music venue relief | Cuts the eligible bill by a further 15% for 2026-27 | Pubs and live music venues meeting the criteria |
| Transitional relief | Caps year-on-year bill increases by rateable value band | Properties whose bills rose sharply at the revaluation |
| Supporting small business relief | Caps bills for businesses that lost small business rate relief at the revaluation | Ratepayers who lost SBRR on 1 April 2026 |
| Small business rate relief | 100% relief up to £12,000 RV, tapering to zero by £15,000 | Single-property businesses under £15,000 RV |
The layers are not mutually exclusive. A qualifying pub calculates its initial liability on the RHL multiplier, then applies the 15% reduction, and transitional or supporting small business relief can still apply alongside. In 2027-28 and 2028-29 the pub relief itself is replaced by a real-terms freeze on eligible bills.
Why your pub's bill still varies
Two pubs on the same street can end up with very different bills after 1 April 2026. The main drivers:
- The revaluation. Rateable values were reset across the country, and a pub whose modelled rent rose faster than its neighbours' will feel it.
- Which multiplier the council applied. A pub wrongly classified as non-RHL pays 43.2p or 48p instead of 38.2p or 43p — worth checking the multiplier column on the bill.
- Transitional relief caps. 2026-27 increases are capped at 5% for rateable values up to £20,000 (£28,000 in London), 15% between £20,001 and £100,000, and 30% above £100,000.
- Second properties. Small business rate relief on a main property now continues for 36 months after taking on a second property, for second properties taken on or after 27 November 2025, instead of 12 months.
- Property splits and mergers. A beer garden, function room or car park assessed separately changes the totals.
- Local administration. Councils decide eligibility against the statutory definitions, and practice on marginal cases varies.
What if the 15% relief is not showing on your bill
First, check the bill itself: the relief line and the multiplier used. Councils say relief is awarded automatically to properties they believe qualify, and an omission is usually an administrative gap rather than a rejected claim — applying with your rates reference and your reasons is the fix. If the property details on the rating list look wrong instead, the valuation itself can be challenged. A rejected challenge is not the end of the road: you can still appeal to an independent tribunal, and a rejected appeal has known causes you can address before resubmitting.
Can a bar or nightclub claim pub relief
Bars and nightclubs are named in the statutory scope of the RHL multipliers, so they get the lower 38.2p or 43p rate. The dedicated 15% pub relief is narrower: the property must be wholly or mainly a pub — free entry, drinking without food, drinks bought at a bar — or a venue wholly or mainly used for live music performances. A bar that happens to meet all of those characteristics may qualify; a nightclub or a members-bar-first venue generally will not. Your council decides, and a marginal case is worth a written enquiry rather than an assumption.
When relief alone is not enough
Relief reduces the rate; it does nothing about a rateable value that is wrong. If your pub's rateable value no longer matches the evidence — rents, floor areas, how the premises are actually used — a Check and Challenge with the Valuation Office Agency is the route, with statutory deadlines that are easy to miss. Appeal My Rates UK assesses a pub's case free by phone, handles the full Check, Challenge and Appeal process, and confirms its fee basis in writing — most instructions are no win, no fee, though some carry fixed fees. If you would rather compare before instructing, see how the best business rates consultants for pubs and bars are evaluated.
FAQ
How much pub relief will my pub get in 2026-27?
Eligible pubs and live music venues in England get a 15% reduction on their 2026-27 business rates bills, worth about £1,650 for the average pub according to the government. The discount is applied by your council on top of the RHL multipliers.
Do pubs still get retail, hospitality and leisure relief in 2026?
No. The temporary RHL relief ended on 31 March 2026. It was replaced by permanent lower multipliers for qualifying RHL properties: 38.2p below a £51,000 rateable value and 43p between £51,000 and £499,999.
What makes a pub qualify for the 15% relief?
The property must be wholly or mainly used as a pub or live music venue, open to the general public with free entry except for occasional entertainment, allow drinking without food, and permit drinks to be purchased at a bar.
Is pub relief automatic?
Councils award it automatically where they believe the criteria are met, and it should show on your 2026-27 annual bill. If it is missing, apply to your council with your business rates reference and your reasons for qualifying.
What happens to pub rates after 2026-27?
Eligible pubs’ business rates bills are frozen in real terms for 2027-28 and 2028-29, replacing the 15% discount for those years. A further targeted reduction for pubs, social clubs and live music venues has been announced to follow.
Can I appeal my pub’s rateable value while receiving relief?
Yes. A valuation challenge through the VOA’s Check and Challenge runs separately from any relief your council applies, so both can proceed at the same time.
Do bars and nightclubs get the lower RHL multipliers?
Yes. Bars and nightclubs are within the statutory scope of the RHL multipliers, but the dedicated 15% pub relief applies only to properties wholly or mainly used as pubs or live music venues.
One last thing
Before anything else, read the multiplier column on your 2026-27 bill. If it shows 43.2p or 48p and your pub is open to the public selling food and drink at a bar, the council may have applied the wrong multiplier — that five-minute check can be worth more than any appeal, and it costs nothing.
Let us handle your case
Appeal My Rates UK will review your pub’s rateable value, reliefs and bill free before any fee is agreed.
Related guides
- VOA Check, Challenge, Appeal: a step-by-step 2026 guide
- How much can I save by challenging my business rates?
- How much does a business rates surveyor charge?
